<!-- Insert Image 1 (hero) here -->  <p>Comparing San Antonio builder incentives can turn a fun home search into a math class fast. One builder in Cibolo offers a lower rate. One in Schertz promises thousands toward closing costs. One in New Braunfels advertises a straight price cut. The biggest number on the flyer doesn't always mean the biggest savings for you — the right pick depends on your monthly payment, your upfront cash, and how long you plan to stay in the home.</p>  <h2>Rate Buydown, Closing Costs, or Price Reduction — Which Wins?</h2>  <h3>Rate Buydown</h3> <p>A rate buydown uses builder funds to lower your mortgage interest rate, either temporarily for the first year or two, or permanently for the life of the loan. It often delivers the biggest monthly savings, especially while rates stay elevated — but builders usually require their preferred lender to unlock it. Ask whether the rate is temporary or permanent, what the real APR is once fees are included, and don't assume you can simply refinance out later if rates don't cooperate.</p>  <h3>Closing-Cost Assistance</h3> <p>This credit reduces what you need at the closing table — often covering lender fees, title costs, prepaid taxes and insurance, or discount points. It's the right move if you'd rather keep cash for movers, blinds, appliances, and the inevitable home-improvement run every new homeowner makes. Loan programs cap how much a builder can contribute, so confirm with your lender exactly what the credit can be applied to before you count on it.</p>  <!-- Insert Image 2 (comparison graphic) here -->  <h3>Price Reduction</h3> <p>Lowering the purchase price strengthens your equity from day one and modestly reduces your payment, down payment, and a few sales-price-based closing costs. It doesn't always beat a strong rate buydown on monthly savings, though — a $20,000 incentive applied to your rate can move your payment more than a $20,000 price cut. Compare both using real loan estimates, not a quick calculator app.</p>  <h2>What Military and VA Buyers Should Know</h2>  <!-- Insert Image 3 (military/JBSA) here -->  <p>Relocating to JBSA Randolph, Fort Sam Houston, or Lackland AFB adds a layer of complexity: VA loans have their own rules on seller and builder contributions and what counts as a customary closing cost. An incentive structured cleanly on a conventional loan can look different on a VA file. Make sure your lender and the builder's team both have VA new-construction experience — getting this wrong can cost you the incentive or delay closing during a PCS timeline that has no flexibility.</p>  <h2>How to Compare Offers Line by Line</h2> <p>Get these eight numbers in writing before you choose:</p> <ol>   <li>Estimated monthly principal and interest</li>   <li>Total cash required at closing</li>   <li>Whether the rate is temporary or permanent</li>   <li>Interest rate, APR, points, and lender fees</li>   <li>Preferred-lender requirements</li>   <li>Expected savings over your planned ownership timeline</li>   <li>Purchase price and appraised value</li>   <li>Deadlines, exclusions, or fine print</li> </ol>  <h2>Don't Skip the Inspection</h2> <p>Even on a great incentive, get an independent third-party inspection and a separate sewer scope before closing — on a finished spec home too, and before the builder's own walk-through. Incentives are negotiable. Structural and plumbing issues aren't, and the builder's walk-through isn't a substitute for an inspector working for you.</p>  <h2>If You're Selling, This Applies to You Too</h2> <p>Builder incentives compete with your listing, not just each other. A buyer weighing your resale home against new construction in Cibolo or Schertz may be comparing your price against a builder's rate buydown down the street. Knowing what builders are offering right now helps us price and position your home so it competes on more than curb appeal.</p>  <h2>The Bottom Line</h2> <p>Builder incentives shift constantly based on inventory, timelines, and sales goals — a completed home in Cibolo can carry a different offer than the same floor plan in Schertz or Converse within the same week. Get every incentive in writing, read the loan estimate line by line, and confirm upfront whether accepting one benefit disqualifies you from another. Sometimes the rate buydown wins. Sometimes protecting your cash matters more. Ready to see what builders around Greater San Antonio are actually offering? Explore homes by city on my new-construction page, and we'll run the real numbers together.</p>  <!-- Insert Image 4 (CTA or headshot) here -->  <h2>FAQ</h2>  <h3>What is a builder rate buydown?</h3> <p>A builder rate buydown is money the builder contributes toward lowering your mortgage interest rate, either temporarily for the first one to two years of the loan or permanently for its full term. It's typically funded through the builder's preferred lender and shows up as a lower rate on your loan estimate rather than as cash back to you.</p>  <h3>Do I have to use the builder's preferred lender to get the incentive?</h3> <p>In most cases, yes — builders tie their strongest incentives to financing through their in-house or preferred lender, since that's how they fund the buydown or credit. You can usually still use an outside lender, but you'll likely lose some or all of the incentive, so it's worth comparing both scenarios side by side before deciding.</p>  <h3>Is a price reduction or a closing cost credit better?</h3> <p>There's no universal answer — a price reduction lowers what you owe and builds equity immediately, while a closing cost credit keeps more cash in your pocket at closing. The better choice depends on whether you're short on cash to close or focused on long-term equity, so run both through an actual loan estimate rather than guessing.</p>  <h3>Can VA buyers use builder incentives in San Antonio?</h3> <p>Yes, VA buyers can absolutely use builder incentives, but VA loans have specific rules about which costs qualify as customary and how much a builder can contribute. Working with a lender and builder team experienced in VA new construction ensures the incentive is structured correctly and won't cause delays during your closing.</p>  <h3>How much are builder incentives typically worth in San Antonio?</h3> <p>Builder incentives around Greater San Antonio commonly range from a few thousand dollars up to $20,000-$30,000 or more, depending on the community, the home's inventory status, and how motivated the builder is to sell that particular home. Completed spec homes and homes that have sat on the market longer tend to carry the largest incentives.</p>  <h3>Are builder incentives negotiable?</h3> <p>Often, yes — especially on completed inventory homes the builder is eager to move before the end of a sales period or fiscal quarter. It doesn't hurt to ask whether additional incentives are available, particularly if you're flexible on move-in timing or willing to use the builder's preferred lender.</p>  <p><em>Venus Marshall is a Realtor® with Real Broker, LLC, serving Greater San Antonio since 2016 with a focus on military PCS relocation, VA home buyers, and new construction.</em></p>


Comparing San Antonio builder incentives can turn a fun home search into a math class fast. One builder in Cibolo offers a lower rate. One in Schertz promises thousands toward closing costs. One in New Braunfels advertises a straight price cut. The biggest number on the flyer doesn't always mean the biggest savings for you — the right pick depends on your monthly payment, your upfront cash, and how long you plan to stay in the home.


Rate Buydown, Closing Costs, or Price Reduction — Which Wins?
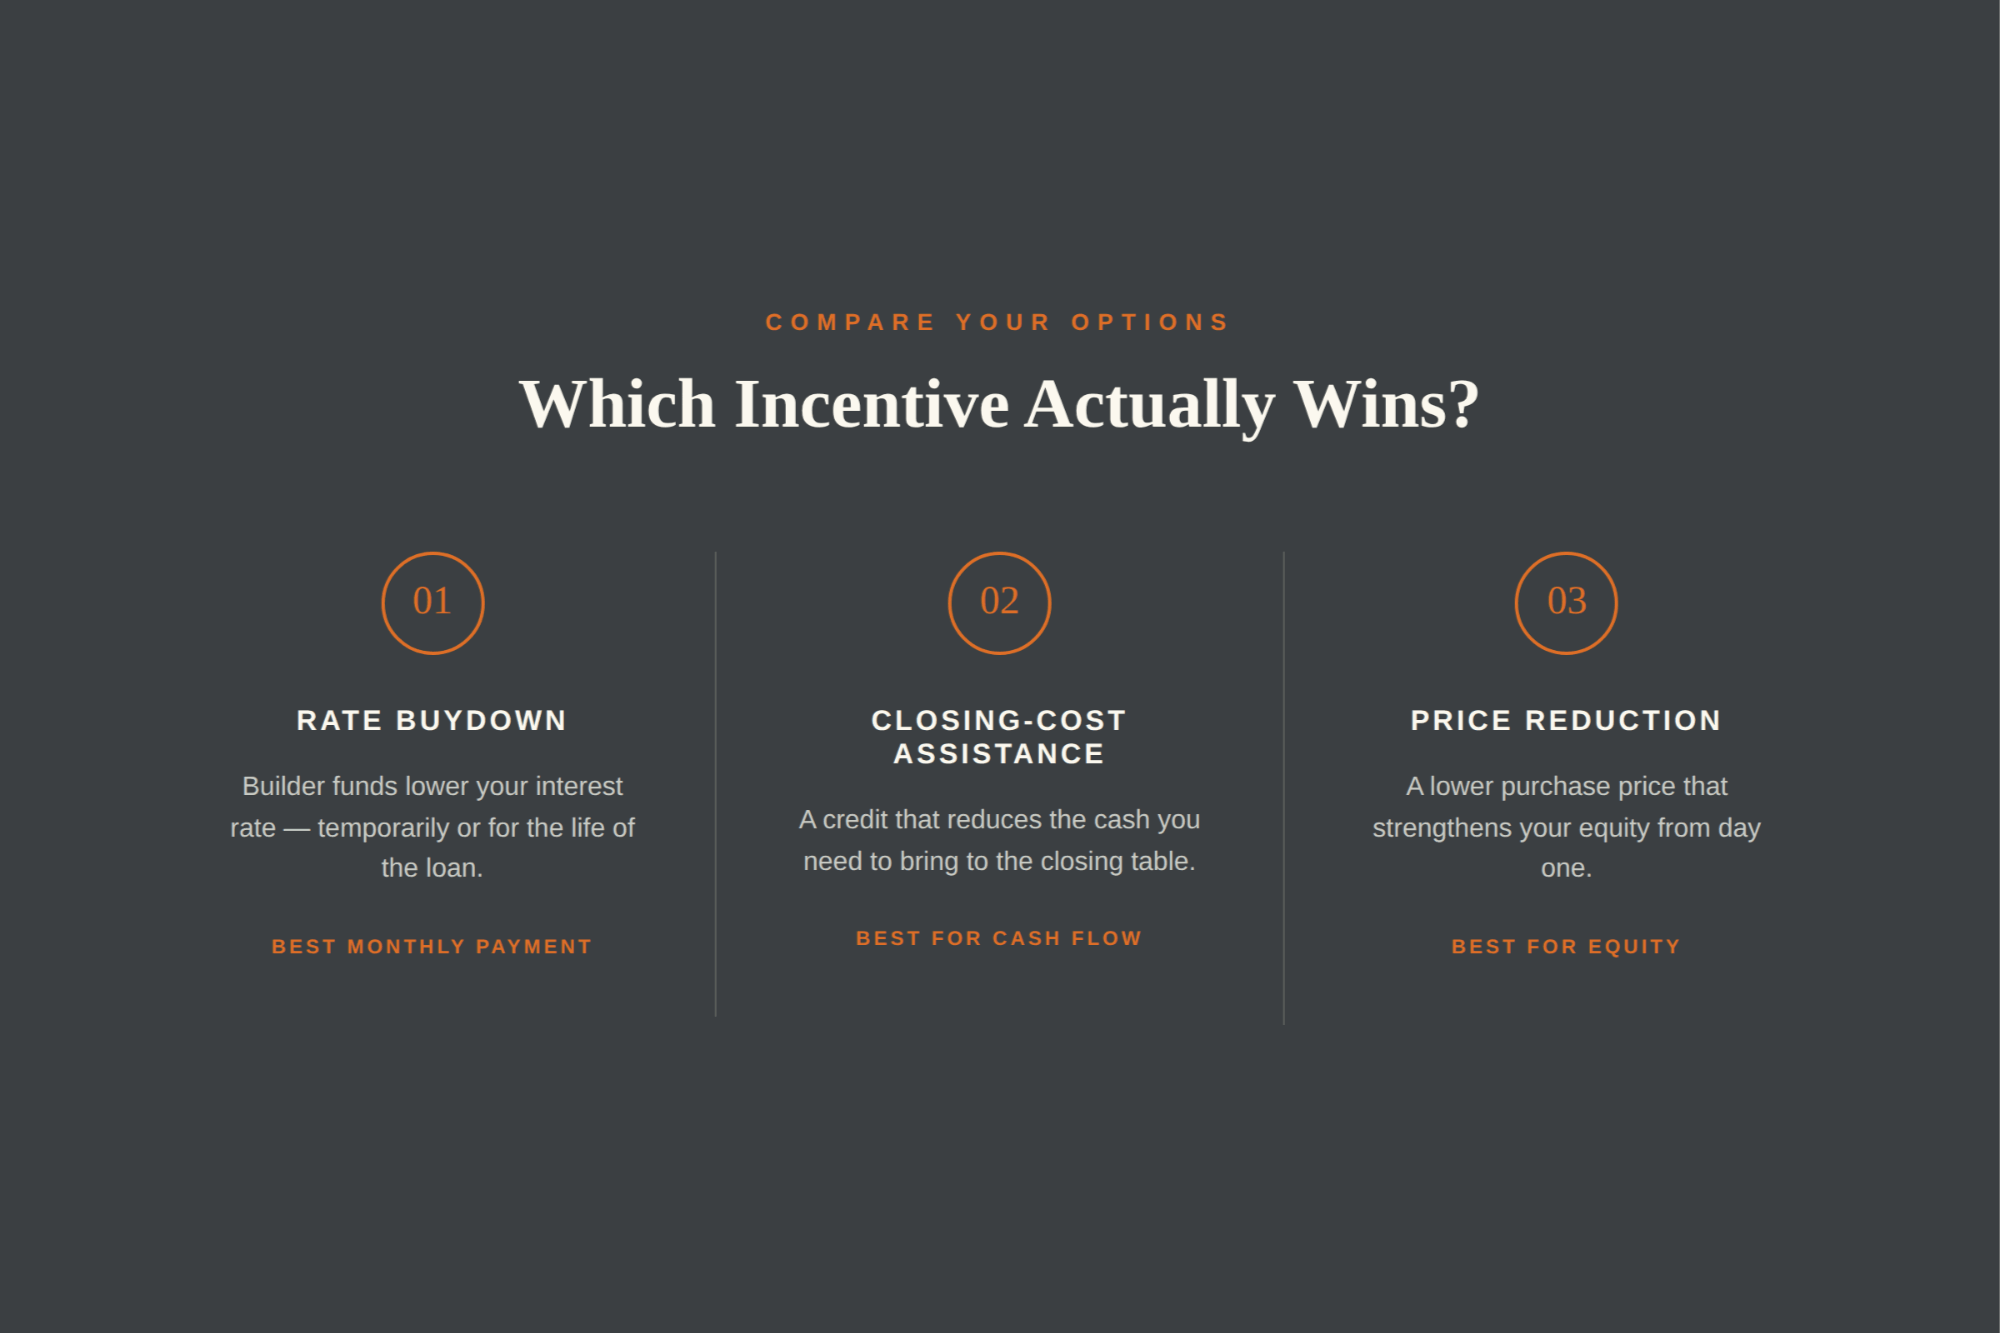
Comparison chart of rate buydown, closing cost assistance, and price reduction incentives


Rate Buydown

A rate buydown uses builder funds to lower your mortgage interest rate, either temporarily for the first year or two, or permanently for the life of the loan. It often delivers the biggest monthly savings, especially while rates stay elevated — but builders usually require their preferred lender to unlock it. Ask whether the rate is temporary or permanent, what the real APR is once fees are included, and don't assume you can simply refinance out later if rates don't cooperate.

Closing-Cost Assistance

This credit reduces what you need at the closing table — often covering lender fees, title costs, prepaid taxes and insurance, or discount points. It's the right move if you'd rather keep cash for movers, blinds, appliances, and the inevitable home-improvement run every new homeowner makes. Loan programs cap how much a builder can contribute, so confirm with your lender exactly what the credit can be applied to before you count on it.

Price Reduction

Lowering the purchase price strengthens your equity from day one and modestly reduces your payment, down payment, and a few sales-price-based closing costs. It doesn't always beat a strong rate buydown on monthly savings, though — a $20,000 incentive applied to your rate can move your payment more than a $20,000 price cut. Compare both using real loan estimates, not a quick calculator app.


What Military and VA Buyers Should Know
Military and VA buyer guide for builder incentives near JBSA Randolph, Fort Sam Houston, and Lackland AFB


Relocating to JBSA Randolph, Fort Sam Houston, or Lackland AFB adds a layer of complexity: VA loans have their own rules on seller and builder contributions and what counts as a customary closing cost. An incentive structured cleanly on a conventional loan can look different on a VA file. Make sure your lender and the builder's team both have VA new-construction experience — getting this wrong can cost you the incentive or delay closing during a PCS timeline that has no flexibility.

How to Compare Offers Line by Line

Get these eight numbers in writing before you choose:

  1. Estimated monthly principal and interest
  2. Total cash required at closing
  3. Whether the rate is temporary or permanent
  4. Interest rate, APR, points, and lender fees
  5. Preferred-lender requirements
  6. Expected savings over your planned ownership timeline
  7. Purchase price and appraised value
  8. Deadlines, exclusions, or fine print


Don't Skip the Inspection

Even on a great incentive, get an independent third-party inspection and a separate sewer scope before closing — on a finished spec home too, and before the builder's own walk-through. Incentives are negotiable. Structural and plumbing issues aren't, and the builder's walk-through isn't a substitute for an inspector working for you.

If You're Selling, This Applies to You Too

Builder incentives compete with your listing, not just each other. A buyer weighing your resale home against new construction in Cibolo or Schertz may be comparing your price against a builder's rate buydown down the street. Knowing what builders are offering right now helps us price and position your home so it competes on more than curb appeal.

The Bottom Line

Builder incentives shift constantly based on inventory, timelines, and sales goals — a completed home in Cibolo can carry a different offer than the same floor plan in Schertz or Converse within the same week. Get every incentive in writing, read the loan estimate line by line, and confirm upfront whether accepting one benefit disqualifies you from another. Sometimes the rate buydown wins. Sometimes protecting your cash matters more. Ready to see what builders around Greater San Antonio are actually offering? Explore homes by city on my new-construction page, and we'll run the real numbers together.


Explore San Antonio new construction homes with Venus Marshall, Real Broker LLC


FAQ

What is a builder rate buydown?

A builder rate buydown is money the builder contributes toward lowering your mortgage interest rate, either temporarily for the first one to two years of the loan or permanently for its full term. It's typically funded through the builder's preferred lender and shows up as a lower rate on your loan estimate rather than as cash back to you.

Do I have to use the builder's preferred lender to get the incentive?

In most cases, yes — builders tie their strongest incentives to financing through their in-house or preferred lender, since that's how they fund the buydown or credit. You can usually still use an outside lender, but you'll likely lose some or all of the incentive, so it's worth comparing both scenarios side by side before deciding.

Is a price reduction or a closing cost credit better?

There's no universal answer — a price reduction lowers what you owe and builds equity immediately, while a closing cost credit keeps more cash in your pocket at closing. The better choice depends on whether you're short on cash to close or focused on long-term equity, so run both through an actual loan estimate rather than guessing.

Can VA buyers use builder incentives in San Antonio?

Yes, VA buyers can absolutely use builder incentives, but VA loans have specific rules about which costs qualify as customary and how much a builder can contribute. Working with a lender and builder team experienced in VA new construction ensures the incentive is structured correctly and won't cause delays during your closing.

How much are builder incentives typically worth in San Antonio?

Builder incentives around Greater San Antonio commonly range from a few thousand dollars up to $20,000-$30,000 or more, depending on the community, the home's inventory status, and how motivated the builder is to sell that particular home. Completed spec homes and homes that have sat on the market longer tend to carry the largest incentives.

Are builder incentives negotiable?

Often, yes — especially on completed inventory homes the builder is eager to move before the end of a sales period or fiscal quarter. It doesn't hurt to ask whether additional incentives are available, particularly if you're flexible on move-in timing or willing to use the builder's preferred lender.

Venus Marshall is a Realtor® with Real Broker, LLC, serving Greater San Antonio since 2016 with a focus on military PCS relocation, VA home buyers, and new construction.

GET IN TOUCH